Hello Friends of Cherry Run Camp,
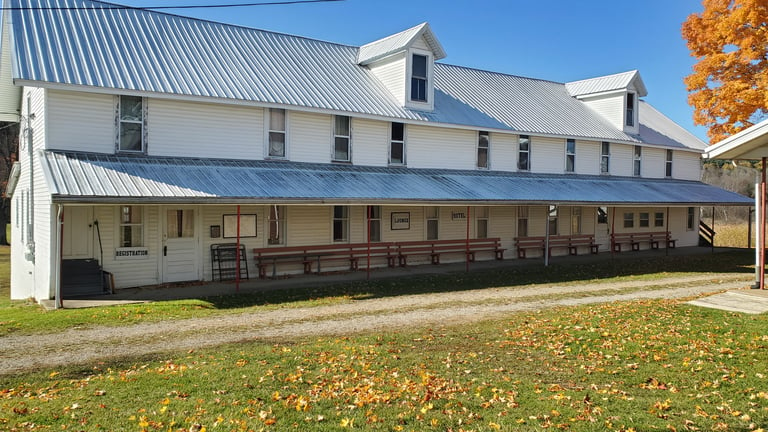
As you may know, Cherry Run Camp has a fresh vision to increase family housing and
renovate the old hotel. Work is already underway, and God has been so faithful to provide! To
help achieve this vision, the Board of Directors has approved a capital campaign with a goal of raising $250,000.
As you prayerfully consider your year-end giving, I want to provide some basic information regarding some unique giving avenues called Qualified Charitable Distributions and Donor Advised Funds. If either of these avenues of giving interest you, I?d encourage you to speak with your Financial Advisor.
Thank you for helping Cherry Run Camp make disciples of Jesus Christ in the Wesleyan Holiness tradition! ? Rev. Brett Dinger, Vice-President
Qualified Charitable Distribution (QCD)
- A Qualified Charitable Distribution is a nontaxable distribution by the custodian
or trustee of a taxpayer’s IRA (some exceptions apply) made directly to an
organization eligible to receive tax deductible contributions. Not all charitable
organizations are eligible. - A taxpayer must be at least age 70? when the distribution is made (not just in
the year the taxpayer attains age 70?). - The 2025, maximum inflation adjusted annual amount is $108,000.
- If the taxpayer files a joint return, the taxpayer’s spouse can also make a QCD.
- A QCD will count towards the taxpayer’s required minimum distribution (RMD).
Donor Advised Fund (DAF)
- A Donor Advised Fund is a charitable investment account that provides simple,
flexible, and efficient ways to manage charitable giving. The money that goes
into a Donor Advised Fund becomes an irrevocable transfer to a public charity
with the specific intent of funding charitable gifts. This public charity serves as
the administrator of the DAF. - The Donor may be an individual, family, trust, Private Foundation, or
corporation. - The Donor may make grant recommendations or provide advice on distributions
from the fund to qualified charitable organizations (can be multiple
organizations). The donor may not direct or place restrictions on the fund’s
distribution. - The assets contributed receive tax-free investment growth which allows
compounding for endowing the Donor’s charitable giving effort.